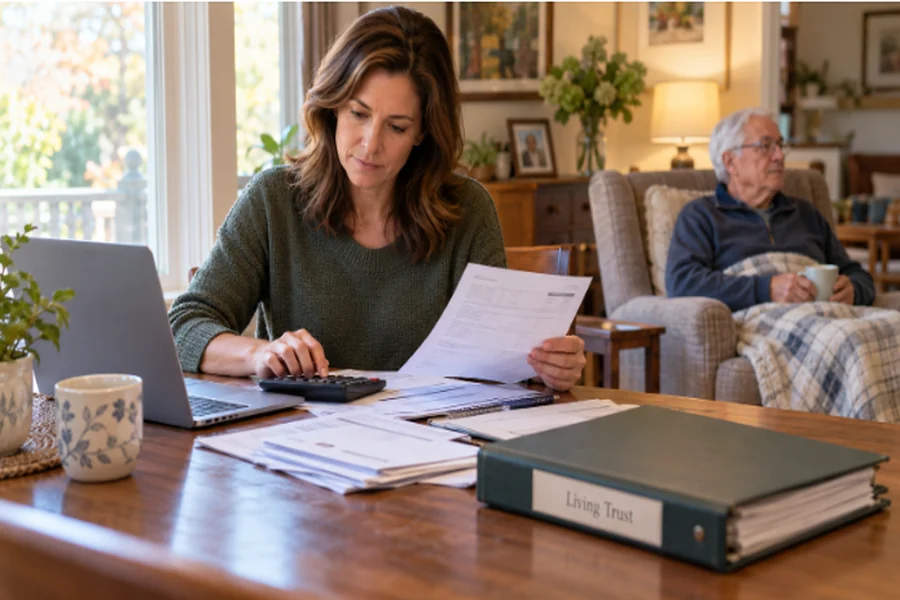
A living trust can help keep your finances running if illness or injury leaves you unable to manage them. Mortgage payments, insurance premiums, and everyday bills still need attention, even when you cannot review statements or speak with your bank.
That can put relatives in a difficult position. They may know what needs paying but lack legal authority to use your accounts. A properly prepared and funded revocable living trust lets someone you choose manage trust assets for your benefit.
How The Arrangement Works
When you establish a revocable living trust, you generally name yourself as trustee and continue managing the assets you transfer into it. You also name a successor trustee who can take over under the conditions described in the document.
During incapacity, that person manages trust property according to your instructions. Depending on the trust’s terms, this may include paying household expenses, overseeing investments, collecting rental income, or covering care costs.
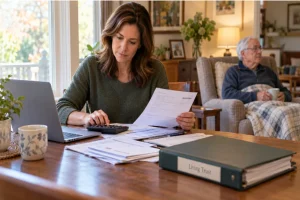
For example, someone recovering from a serious stroke may need months of assistance. Their successor trustee could use a trust bank account to pay the mortgage and arrange home care payments.
When The Successor Trustee Steps In
A diagnosis does not automatically give a relative control over your finances. The trust should explain how incapacity is determined and what evidence is required before a successor trustee acts.
Some documents require written assessments from physicians. Others use different procedures. A living trust attorney can explain these provisions and help establish a practical process for transferring responsibility, including what happens if you recover.
Clear instructions can reduce uncertainty during a stressful period. They also help banks and family members understand who has authority to act.
Why Funding The Trust Matters
Signing the document alone does not place your assets under the trustee’s control. Appropriate assets must actually be transferred into the trust, a process commonly called funding.
This may involve changing ownership of certain bank accounts or recording a deed for real estate. Retirement accounts generally require different treatment, so get advice before changing ownership or beneficiary designations.
A successor trustee’s authority covers trust assets. An account left solely in your individual name may require another legal arrangement before anyone can manage it.
Keeping Financial Help Accountable
The successor trustee must follow the trust and applicable law. Their role includes duties such as careful money management and acting for the beneficiaries’ benefit.
Practical safeguards include:
- Keeping accurate records of payments and transactions.
- Separating trust property from the trustee’s personal money.
- Retaining receipts, statements, and supporting documents.
- Following any reporting requirements in the trust or state law.
Coordinating Other Important Documents
A trust does not handle every financial or personal decision. A durable power of attorney can authorize someone to address financial matters outside the trust, while a health care proxy addresses medical decisions.
An estate planning attorney can coordinate these documents so responsibilities are clear. Review the plan when accounts, relationships, or your chosen helpers change, and make sure your successor knows where the documents and asset records are kept. Naming an alternate helps if your first choice becomes unavailable.

Passionate about exploring diverse ideas and sharing inspiration, I curate content that sparks curiosity and encourages personal growth. Join me at ElementalNest.com for insights across a wide range of topics.